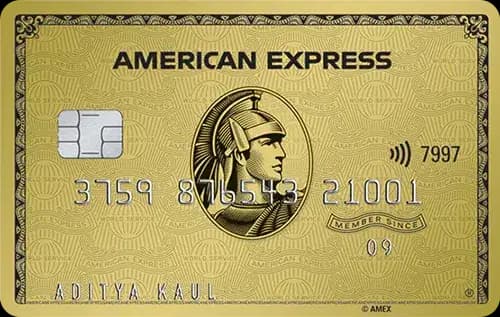
Quick Verdict
- For everyday spending, the Standard Chartered Ultimate Credit Cardⓘ wins with a much higher base reward rate of 3.33% compared to 0.5% on the American Express Gold Credit Cardⓘ.
- For travel and lounge access, the Standard Chartered Ultimate also leads, offering 4 international lounge visits per year and 8 domestic lounges, whereas the Amex Gold provides only 8 domestic lounges and no international lounge access.
- The American Express Gold Credit Card is cheaper to hold with an annual fee of Rs 4,500 plus Rs 1,000 joining fee, compared to the Standard Chartered Ultimate’s Rs 5,000 annual and Rs 5,000 joining fee.
- Choose the Amex Gold if you want a lower fee card with decent domestic lounge access and premium dining or shopping discounts. Opt for the Standard Chartered Ultimate if you prioritize high rewards, international lounges, and premium travel benefits despite the higher fees.
Side by Side
| Detail | American Express Gold Credit Cardⓘ | Standard Chartered Ultimate Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,500 | Rs 5,000 |
| Joining fee | Rs 1,000 | Rs 5,000 |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 0.5% | 3.33% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | rewards, travel, shopping | rewards, travel, lounge, premium, shopping |
Rewards Compared
Spending Rs 10,000 on the American Express Gold Credit Cardⓘ earns Rs 50 worth of points, reflecting its base reward rate of 0.5%. This modest return suits users who value the card’s premium benefits like dining discounts and hotel offers more than pure cashback or rewards. The card’s rewards are points-based, which may require redemption through American Express’s platform.
In contrast, the Standard Chartered Ultimate Credit Cardⓘ delivers Rs 333 in rewards for the same Rs 10,000 spend, a significant jump due to its 3.33% reward rate. This makes it highly attractive for heavy spenders seeking maximum rewards. Additionally, it offers 5% cashback on duty-free spends and rewards redeemable for shopping vouchers or charity, adding flexibility. The higher reward rate means the card covers its higher fees much sooner for active users.
Fees Compared
The American Express Gold Credit Cardⓘ charges a joining fee of Rs 1,000 and an annual fee of Rs 4,500. There is no specified fee waiver on spend, and the card requires Rs 9,00,000 in annual spending to cover its fee purely through base rewards. This high break-even reflects the low base reward rate.
The Standard Chartered Ultimate Credit Cardⓘ has a steeper joining fee of Rs 5,000 and an annual fee of Rs 5,000. Like the Amex Gold, no fee waiver on spend is mentioned. However, its high reward rate means the break-even spend to cover fees is about Rs 1,50,150 annually, far lower than the Amex Gold. The extra Rs 500 annual fee compared to Amex Gold is offset by the much higher rewards after just Rs 17,668 in additional spend.
Which One Should You Pick
Choose the American Express Gold Credit Cardⓘ if you want a card with a lower annual fee and joining fee, decent domestic lounge access, and premium benefits like dining discounts, hotel offers, and Apple Store cashback. It suits moderate spenders who value lifestyle perks over high rewards and do not travel internationally often.
Pick the Standard Chartered Ultimate Credit Cardⓘ if you are a high spender looking for maximum rewards, international lounge access, and premium travel benefits including complimentary golf access and medical insurance. It is ideal for frequent travelers and those who can leverage the card’s higher reward rate to offset its higher fees quickly.
In summary, skip the Amex Gold if you want strong rewards or international lounge access. Skip the Standard Chartered Ultimate if you are a light spender or want a lower-cost card focused on domestic perks.
What to Check Before You Apply
- Confirm if the lounge access caps are per year or per quarter and any guest policies.
- Check the redemption value and flexibility of points, especially for the Amex Gold’s Membership Rewards points.
- Understand the fee waiver thresholds and whether monthly or annual spends qualify.
- Consider the forex markup fees carefully if you travel abroad frequently; Standard Chartered Ultimate has a lower 2% fee versus 3.5% on Amex Gold.

Comments
No comments yet
Be the first to share your experience with this card.