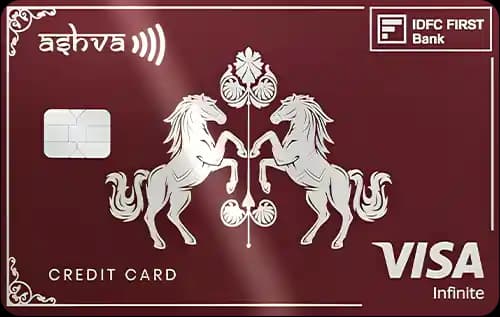
Quick Verdict
- For everyday spending and base rewards, the Marriott Bonvoy HDFC Bank Credit Cardⓘ offers a slightly better return.
- When it comes to travel perks and lounge access, Marriott Bonvoy HDFC Bank Credit Cardⓘ leads with more international and domestic lounge visits.
- The Ashva Credit Cardⓘ is cheaper to hold abroad, thanks to its lower forex markup of 1.5% versus Marriott Bonvoy’s 3.5%.
- Choose Ashva Credit Cardⓘ if you prioritize lower forex costs and premium hotel benefits; go for Marriott Bonvoy HDFC Bank Credit Cardⓘ if you want richer lounge access and higher category rewards.
Side by Side
| Detail | Ashva Credit Cardⓘ | Marriott Bonvoy HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 3,000 |
| Joining fee | Rs 2,999 | Rs 3,000 |
| Reward rate | 1.25% | 1.3% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 12 per year |
| International lounge | 4 per year | 12 per year |
| Forex markup | 1.5% | 3.5% |
| Best suited for | premium, travel, lounge, rewards, shopping | travel, premium, lounge, rewards, shopping |
Rewards Compared
The Ashva Credit Cardⓘ gives an effective reward of Rs 125 on every Rs 10,000 spent, rising to Rs 250 in dining and travel categories. This is attractive for users who focus on these categories and want decent returns with a relatively low forex markup. The card’s base reward rate of 1.25% means Rs 125 back on general spends.
In comparison, the Marriott Bonvoy HDFC Bank Credit Cardⓘ offers Rs 130 per Rs 10,000 spent at the base level and Rs 260 in travel and dining categories. The slightly higher category rates and base reward rate reflect its positioning for frequent travelers and premium spenders who want to maximize reward accumulation, especially within travel-related spends.
Fees Compared
Ashva Credit Cardⓘ and Marriott Bonvoy HDFC Bank Credit Cardⓘ charge similar joining and annual fees of around Rs 3,000 annually. Ashva’s fee stands at Rs 2,999 for both joining and renewal, while Marriott Bonvoy’s fees are Rs 3,000 each. Neither card mentions an explicit fee waiver threshold, so annual fees are expected upfront.
The break-even spend to cover the annual fee through base rewards is about Rs 2,39,920 for Ashva Credit Cardⓘ and Rs 2,30,769 for Marriott Bonvoy HDFC Bank Credit Cardⓘ. The slight difference means you need to spend roughly Rs 2,000 more on Ashva Credit Cardⓘ to offset the fee cost with base rewards alone, reflecting Marriott Bonvoy’s marginally better return rate.
Which One Should You Pick
Pick the Ashva Credit Cardⓘ if you are a premium traveler who values a lower forex markup at 1.5%, combined with luxury hotel perks including free stays at ITC Hotels/Elivaas and up to 20% dining discounts. The card is also suited for those who want moderate lounge access and concierge services without paying a premium forex fee.
Choose the Marriott Bonvoy HDFC Bank Credit Cardⓘ if you want superior lounge access with 12 free domestic and international visits per year, plus Marriott Bonvoy Silver Elite status and golf benefits. It is ideal for frequent Marriott hotel guests and travelers looking to maximize rewards on dining and travel spends despite the higher 3.5% forex markup.
Skip Ashva Credit Cardⓘ if you do significant foreign currency spending where forex fees matter most. Skip Marriott Bonvoy HDFC Bank Credit Cardⓘ if you rarely use lounges or Marriott properties and want to avoid the higher forex fees.
What to Check Before You Apply
- Confirm the exact caps on lounge visits and whether guest entries are included.
- Verify redemption value of points and if category bonuses have caps or exclusions.
- Calculate the monthly spend needed to effectively waive the annual fee if any waiver applies.
- Check the forex markup carefully if you plan to use the card abroad frequently.
- Ensure the airport lounges offered are at your preferred airports and terminals.

Comments
No comments yet
Be the first to share your experience with this card.