Quick Verdict
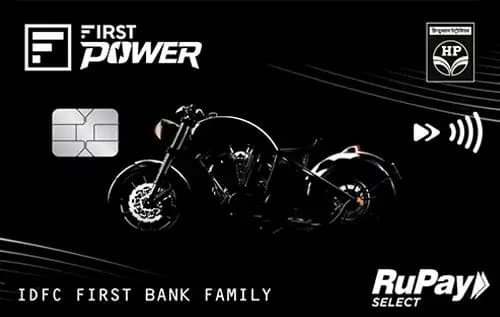
- For everyday spend, the Yes Bank Rupay Credit Card ⓘ wins with a higher base reward rate of 1% compared to 0.75% on the IDFC HPCL First Power Credit Card ⓘ.
- For fuel, grocery, and utilities categories, the IDFC HPCL First Power Credit Card ⓘ leads with 5% rewards, significantly higher than Yes Bank’s 3% on grocery and dining.
- The Yes Bank Rupay card is cheaper to hold with zero joining and annual fees, while IDFC charges Rs 199 for both, which can be waived on Rs 50,000 annual spend.
- Pick the IDFC card if you frequently spend on fuel and utilities, or want a first card for fuel benefits. Choose the Yes Bank Rupay for a no-fee card with domestic lounge access and better base rewards on general spends.
Side by Side
| Detail | IDFC HPCL First Power Credit Card ⓘ | Yes Bank Rupay Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 199 | Nil (lifetime free) |
| Joining fee | Rs 199 | Nil (lifetime free) |
| Fee waiver on spend | Rs 50,000 | Rs 75,000 |
| Reward rate | 0.75% base, 5% fuel, grocery, utilities | 1% base, 3% grocery, dining, 1% UPI |
| Reward type | Points | Points |
| Domestic lounge | None | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Fuel, UPI-Rupay, First card | UPI-Rupay, Rewards, Grocery, First card, Shopping |
Rewards Compared
The IDFC HPCL First Power Credit Card ⓘ offers Rs 75 back on a Rs 10,000 general spend at its base 0.75% rate. However, it shines in fuel, grocery, and utilities with a 5% reward rate, yielding Rs 500 back on Rs 10,000 spent in each of these categories, making it highly attractive for targeted everyday expenses. The card also provides a welcome benefit of a Rs 250 gift voucher on the first HPCL fuel transaction and up to 5% cashback on the first EMI transaction capped at Rs 1,000.
In contrast, the Yes Bank Rupay Credit Card ⓘ gives Rs 100 back on Rs 10,000 spent at its 1% base rate, which is higher than IDFC’s base reward. For grocery and dining, it offers 3% returns, equating to Rs 300 on Rs 10,000, and 1% on UPI transactions for Rs 100 back on Rs 10,000. While it does not match IDFC’s 5% category returns, its no-fee structure and the ability to earn steady rewards across multiple categories including shopping make it a solid choice for diversified spending.
Fees Compared
The IDFC HPCL First Power Credit Card ⓘ charges Rs 199 for joining and Rs 199 annually. The annual fee can be waived if you spend Rs 50,000 per year, which breaks down to about Rs 4,167 monthly. The break-even spend at the base rate to cover the fee is Rs 26,533 annually, making the fee worthwhile if you leverage the high 5% category rewards or meet the waiver threshold.
Yes Bank Rupay Credit Card ⓘ has no joining or annual fees, making it a completely free card for the lifetime of ownership. Its fee waiver threshold of Rs 75,000 is largely irrelevant since no fee applies. This zero-fee structure combined with a reasonable reward rate means there is no break-even spend to worry about, adding to its appeal for fee-conscious users.
Which One Should You Pick
Choose the IDFC HPCL First Power Credit Card ⓘ if your spending is heavily weighted towards fuel, groceries, or utilities. The 5% category rewards on these essential spends can deliver significant value, especially if you can meet the Rs 50,000 annual spend requirement to waive the fee. It is also a good pick if you want a first credit card focused on fuel benefits, thanks to its welcome offers and HPCL tie-ups. However, skip this card if you do not spend enough to justify the annual fee or if you prefer lounge access and a fee-free card.
Opt for the Yes Bank Rupay Credit Card ⓘ if you want a no-fee, straightforward rewards card that delivers decent returns on everyday categories like grocery and dining, plus UPI spends. Its domestic lounge benefit of 4 visits per year after meeting a quarterly Rs 50,000 spend gate adds value for occasional travelers. This card suits those who are fee-averse, prefer a wider range of reward categories, and want some lounge access without extra cost. Avoid this card if you do not meet the Rs 50,000 quarterly spend for lounges or if you want higher rewards on fuel.
Overall, the IDFC HPCL First Power Credit Card ⓘ is the best choice for category-focused spenders, especially on fuel and utilities, while the Yes Bank Rupay Credit Card ⓘ appeals to everyday spenders seeking a fee-free card with lounge access and decent rewards.
What to Check Before You Apply
- Confirm the exact category definitions and caps on the 5% rewards for fuel, grocery, and utilities on the IDFC card.
- Understand the redemption value and process of reward points on both cards, as this affects actual returns.
- Verify the monthly spend required to waive the IDFC card fee and ensure your spending pattern fits it.
- Check the forex markup of 3.5% on both cards if you plan to use them abroad, as this adds significantly to costs.
- For Yes Bank Rupay, confirm the quarterly Rs 50,000 spend gate to access domestic lounges and the number of lounges allowed.

Comments
No comments yet
Be the first to share your experience with this card.