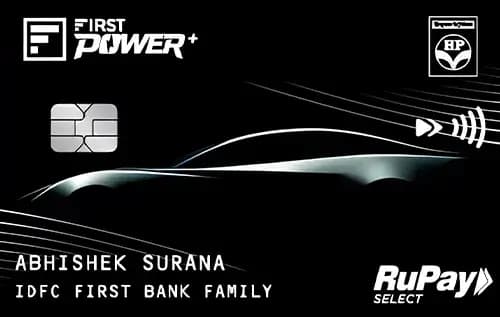
Quick Verdict
- The IndusInd Bank Tiger Credit Cardⓘ wins for everyday spend due to its higher base reward rate of 1% compared to 0.75% on the IDFC card.
- For fuel, grocery, and utility spends, the IDFC HPCL First Power Plus Credit Cardⓘ delivers superior returns with category rates up to 6.5%.
- The IndusInd card is cheaper to hold with zero joining and annual fees, while the IDFC card charges Rs 499 annually, waivable only on Rs 1.50 lakh annual spend.
- Pick the IDFC card if you spend heavily on fuel and groceries and can meet the fee waiver threshold; choose the IndusInd card if you want a no-fee, simple rewards card with good base returns and some golf perks.
Side by Side
| Detail | IDFC HPCL First Power Plus Credit Cardⓘ | IndusInd Bank Tiger Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 499 | Nil (lifetime free) |
| Joining fee | Rs 499 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | Not applicable |
| Reward rate | 0.75% base; 6.5% fuel; 5% grocery, utilities | 1% base; 2.5% online; 1% UPI |
| Reward type | points | points |
| Domestic lounge | 4 per year (Rs 20,000 monthly spend gate) | 4 per year (Rs 40,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, UPI-Rupay, grocery, lounge | lifetime-free, UPI-Rupay, rewards, lounge, travel |
Rewards Compared
On a Rs 10,000 spend, the IDFC HPCL First Power Plus Credit Cardⓘ yields Rs 75 at its base rate, but this spikes considerably in key categories: Rs 650 on fuel, Rs 500 on grocery and utilities. This makes it highly rewarding for users prioritizing these spends. In contrast, the IndusInd Bank Tiger Credit Cardⓘ offers Rs 100 back as a base reward, with enhanced returns of Rs 250 on online spending and Rs 100 on UPI transactions. While the IndusInd card’s base return is better, the IDFC card’s category bonuses significantly outpace it in fuel and grocery, reflecting a targeted rewards strategy versus a more generalized one.
Fees Compared
The IDFC card carries a joining and annual fee of Rs 499 each, with a fee waiver available on an annual spend of Rs 1.50 lakh, translating to about Rs 12,500 per month. This waiver threshold is relatively high, meaning the cardholder must spend consistently to avoid fees. The break-even point for the base rate to cover the annual fee is approximately Rs 66,533 annually. On the other hand, the IndusInd Tiger Credit Card is a lifetime free product with no joining or annual fees, removing any pressure to meet spend thresholds. This makes it a straightforward choice for fee-sensitive users or those with irregular spend patterns.
Which One Should You Pick
Choose the IDFC HPCL First Power Plus Credit Cardⓘ if you regularly spend on fuel, groceries, and utilities and can comfortably meet the Rs 1.50 lakh annual spend to waive fees. Its higher category rewards and welcome benefits like a Rs 500 gift voucher on HPCL fuel transaction provide strong value for focused users. However, skip it if your spends are low or scattered across categories, as fees may outweigh rewards.
Opt for the IndusInd Bank Tiger Credit Cardⓘ if you prefer a no-fee credit card with a decent base reward rate and occasional category boosts on online and UPI spends. It suits users who want simple, consistent rewards without worrying about fee waivers or high minimum spends. Also, the added golf access may appeal to lifestyle seekers. Avoid this card if you prioritize high category-specific rewards like fuel or grocery.
Overall, the decision boils down to spending habits and fee comfort. Fuel and grocery heavy spenders should lean towards the IDFC card, while those seeking a fee-free, broad-based rewards card will find the IndusInd Tiger Credit Card a better fit.
What to Check Before You Apply
- Verify if the category rewards have caps or limits that could restrict your actual benefits.
- Confirm the redemption options and their value, ensuring points convert conveniently without devaluation.
- Calculate the fee waiver spend carefully and assess if your monthly spend aligns with the Rs 12,500 required on the IDFC card.
- Consider the forex markup of 3.5% on both cards before using them abroad, as this adds a significant cost.

Comments
No comments yet
Be the first to share your experience with this card.