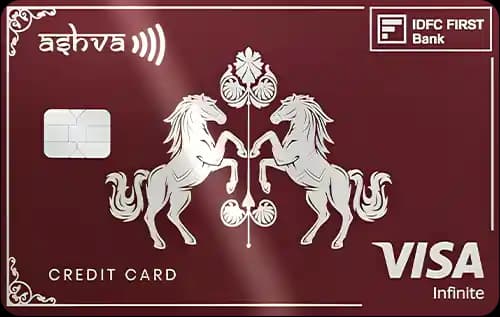
Quick Verdict
- For everyday spend, the Ashva Credit Cardⓘ wins with a higher base reward rate of 1.25% compared to Reliance SBI Card Primeⓘ’s 0.5%.
- When it comes to travel and lounge access, both cards offer 8 domestic and 4 international lounge visits annually, but Ashva Credit Cardⓘ has better travel category rewards and lower forex markup, making it superior for frequent travelers.
- Both cards have the same joining and annual fees of Rs 2,999, but the Reliance SBI Card Primeⓘ offers a fee waiver on Rs 3.00 lakh annual spend, whereas Ashva Credit Cardⓘ does not have a waiver, making Reliance SBI better for high spenders looking to avoid fees.
- Pick Ashva Credit Cardⓘ if you want premium travel perks, better rewards on dining and travel, and lower forex costs. Choose Reliance SBI Card Primeⓘ if your focus is on grocery and online shopping rewards and you can meet the fee waiver threshold.
Side by Side
| Detail | Ashva Credit Cardⓘ | Reliance SBI Card Primeⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 2,999 |
| Joining fee | Rs 2,999 | Rs 2,999 |
| Fee waiver on spend | None | Rs 3.00 lakh |
| Reward rate | 1.25% | 0.5% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 1.5% | 3.5% |
| Best suited for | premium, travel, lounge, rewards, shopping | shopping, grocery, lounge, rewards |
Rewards Compared
The Ashva Credit Cardⓘ delivers Rs 125 back on every Rs 10,000 spent at the base rate. Its category rewards are especially strong in dining and travel, offering 2.5% returns or Rs 250 on Rs 10,000 spend in these categories. This makes it a rewarding card for those spending heavily on travel and dining experiences, where you get double the base reward rate.
The Reliance SBI Card Primeⓘ yields Rs 50 per Rs 10,000 at its base rate, which is less than half that of Ashva Credit Cardⓘ. However, it compensates with 5% returns in grocery and online shopping categories, translating to Rs 500 back on Rs 10,000 spent. This makes it a strong contender for shoppers, especially those with high grocery or online retail expense patterns, where it doubles the returns compared to Ashva Credit Cardⓘ.
Fees Compared
Both cards charge Rs 2,999 as joining and annual fees, making the upfront and recurring costs identical. The Reliance SBI Card Primeⓘ offers a fee waiver if you spend Rs 3.00 lakh annually, which breaks down to Rs 25,000 per month. This is a crucial consideration for heavy spenders who can avoid fees entirely. On the other hand, the Ashva Credit Cardⓘ has no fee waiver, so the Rs 2,999 annual fee is mandatory regardless of spend. The break-even spend to cover the fee through rewards is about Rs 2.40 lakh for Ashva Credit Cardⓘ, which is significantly lower than Rs 6.00 lakh needed for Reliance SBI Card Primeⓘ due to its lower base reward rate.
Which One Should You Pick
Choose the Ashva Credit Cardⓘ if you are a premium traveler who values lounge access, concierge service, and better rewards on dining and travel categories. Its lower forex markup of 1.5% also benefits those who spend abroad frequently. The card’s premium benefits like free stays at ITC Hotels and luxury hotel discounts add to its appeal for travel enthusiasts. However, if you do not spend enough to justify the annual fee, or you focus your spending on groceries, this card may not be the best fit.
Opt for the Reliance SBI Card Primeⓘ if your spending is concentrated in groceries and online shopping and you can meet the Rs 3.00 lakh annual spend threshold to waive the fee. It also suits users who want good lounge access and discounts on hotel bookings and pharmacy purchases. The higher forex markup at 3.5% makes it less attractive for international travel spenders. Those who do not shop frequently at Reliance or cannot meet the waiver criteria should skip this card due to its low base rewards and higher forex cost.
What to Check Before You Apply
- Confirm the categories where higher reward rates apply and whether your spending aligns with these categories.
- Check whether the redemption value of points justifies the effective reward rate promised.
- Be mindful of the monthly spend threshold for fee waiver on Reliance SBI Card Primeⓘ and assess if you can realistically meet it.
- Consider the forex markup if you plan to use the card abroad; Ashva Credit Cardⓘ offers a significantly lower rate at 1.5%.
- Review the lounge access terms including the airports and lounges covered to ensure they match your travel habits.

Comments
No comments yet
Be the first to share your experience with this card.