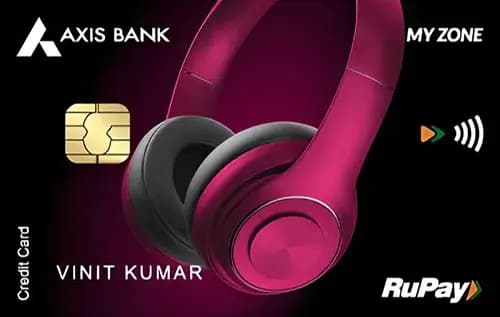
Quick Verdict
- For everyday spending rewards, the Samsung Axis Bank Infinite Credit Cardⓘ offers a significantly higher base reward rate and wins this round.
- When it comes to travel benefits and lounge access, the Samsung Axis Bank Infinite Credit Cardⓘ again leads with more domestic and international lounge visits.
- The Axis Bank My Zone Credit Cardⓘ is cheaper to hold outright, with low joining and annual fees, but the Samsung card is lifetime free, making it cost-effective if you meet the waiver spend.
- Choose the Axis Bank My Zone Credit Cardⓘ if you prioritize dining rewards and want a low-cost starter card. Pick the Samsung Axis Bank Infinite Credit Cardⓘ if you want better rewards on general spends, travel perks, and lounge access.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | Samsung Axis Bank Infinite Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 3.00 lakh | |
| Reward rate | 0.4% base | 1.5% base |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | shopping, lounge, rewards, travel |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ offers a base reward rate of 0.4%, which translates to Rs 40 back on Rs 10,000 spent. Its standout category is dining, where the card delivers a 15% return, or Rs 1,500 on Rs 10,000 dining spend, making it highly attractive for food lovers. Online spends fetch 5%, or Rs 500, which is decent but not exceptional. This card is tailored for users who spend significantly on dining and online shopping but have otherwise moderate everyday spends given the lower base rate.
In contrast, the Samsung Axis Bank Infinite Credit Cardⓘ has a robust 1.5% base reward rate, yielding Rs 150 on Rs 10,000 spend across the board. Its category bonuses are less dramatic than the My Zone card’s dining offer but still valuable: 10% on online spends (Rs 1,000 on Rs 10,000) and 3% on dining (Rs 300 on Rs 10,000). This makes the Samsung card a more balanced rewards card with steady returns on all spending, especially online and general purchases, but less specialized for dining.
Fees Compared
The Axis Bank My Zone Credit Cardⓘ charges Rs 500 each for joining and annual fees. There is no mention of any fee waiver on spending, so these fees are likely unavoidable. The card’s derived break-even for base rewards to cover fees is Rs 1,25,000 annually, meaning you need to spend roughly this much at the base reward rate to justify the fee.
The Samsung Axis Bank Infinite Credit Cardⓘ is lifetime free with no joining or annual fee. However, a fee waiver condition is noted at Rs 3.00 lakh annual spend, or Rs 25,000 monthly, which might relate to unlocking some benefits or maintaining the card status. Since there is no direct fee to waive, this spend threshold is more about perks than cost avoidance. Overall, the Samsung card is cheaper to hold for those who meet or exceed Rs 25,000 monthly spends, making it ideal for higher spenders.
Which One Should You Pick
The Axis Bank My Zone Credit Cardⓘ suits first-time credit card users or those focused on dining rewards and occasional online shopping. Its low fee and strong dining category rates make it a good low-cost option for moderate spenders who want good value on food and entertainment, especially with the SonyLiv subscription welcome benefit. Skip this card if you spend heavily outside dining or want international lounge access.
The Samsung Axis Bank Infinite Credit Cardⓘ is ideal for frequent shoppers, travelers, and lounge users who want a reliable, high base reward rate across categories. Its lifetime free status and superior lounge access (including international lounges) cater well to premium spenders. The Samsung cashback vouchers welcome benefit sweetens the deal for Samsung users. Avoid this card if your monthly spends are well below Rs 25,000 or if you rarely use lounges, as you may not unlock its full value.
Decisively, for rewards and travel perks, the Samsung Axis Bank Infinite Credit Cardⓘ is the better all-rounder, while the Axis Bank My Zone Credit Cardⓘ remains a good budget-friendly choice for dining-focused users.
What to Check Before You Apply
- Confirm the quarterly Rs 50,000 spend gate on domestic lounges with the My Zone cardⓘ to avoid surprise denials.
- Understand the redemption process and value for points, especially since both cards use points but may have different partners or conversions.
- Calculate if your monthly spending can realistically meet the Rs 25,000 waiver threshold for the Samsung Infinite cardⓘ benefits.
- Both cards apply a 3.5% forex markup; check if this is acceptable for your foreign currency spending plans.
- Verify the domestic and international lounge locations and access rules to ensure they match your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.