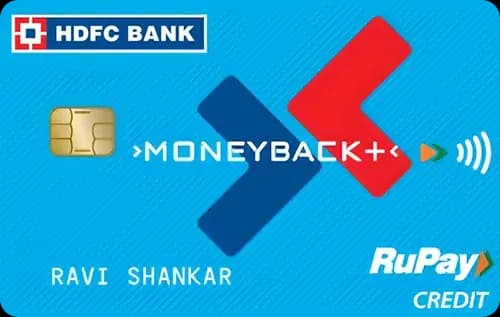
Quick Verdict
- For everyday spend, the Standard Chartered Priority Visa Infinite Credit Card ⓘ offers a higher base reward rate of 1%, making it the better choice.
- For travel and lounge access, the Standard Chartered card clearly leads with unlimited domestic lounge access and 6 international lounge visits annually.
- The HDFC Bank MoneyBack Plus Credit Card ⓘ is cheaper to hold if you spend under Rs 50,000 annually, otherwise its Rs 500 annual fee kicks in.
- Choose HDFC MoneyBack Plus ⓘ if you are a first-time cardholder focused on cashback and online shopping. Opt for Standard Chartered Priority Visa Infinite ⓘ if you want premium benefits, travel perks, and no fees.
Side by Side
| Detail | HDFC Bank MoneyBack Plus Credit Card ⓘ | Standard Chartered Priority Visa Infinite Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 50,000 | None |
| Reward rate | 0.5% base, 3.33% online | 1% base, 2% online and travel |
| Reward type | Points | Points |
| Domestic lounge | None | Unlimited |
| International lounge | None | 6 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | First-card, cashback, shopping | Premium, lounge, travel, lifetime-free, shopping |
Rewards Compared
On a Rs 10,000 spend, the HDFC Bank MoneyBack Plus Credit Card ⓘ yields Rs 50 back at the base rate and Rs 333 when spending online, benefiting heavy online shoppers with a 3.33% effective return. This makes it an attractive option for focused category spenders who shop primarily online. In contrast, the Standard Chartered Priority Visa Infinite Credit Card ⓘ returns Rs 100 at the base rate, doubling the MoneyBack Plus base reward. It offers 2% back on both online and travel categories, which is lower than MoneyBack Plus’s online category but applies also to travel spend, making it more versatile for those who travel often and shop online.
The MoneyBack Plus card’s reward structure targets entry-level users who want decent cashback on online purchases, while Standard Chartered’s card rewards a broader lifestyle pattern with steady 1% returns and category bonuses, plus lounge access that adds tangible value for travelers.
Fees Compared
The HDFC Bank MoneyBack Plus Credit Card ⓘ charges Rs 500 as both joining and annual fees. However, the annual fee is waived if you spend Rs 50,000 annually, which breaks down to Rs 4,167 per month. This means casual users who spend less than this will pay the fee, while more frequent spenders get fee-free benefits. The break-even spend to cover the Rs 500 fee at the base rate is approximately Rs 1,00,000 annually, which aligns with the fee waiver threshold.
Meanwhile, the Standard Chartered Priority Visa Infinite Credit Card ⓘ is lifetime free with no joining or annual fees, making it cost-effective for all spend levels. This no-fee structure combined with premium benefits like lounge access and lower forex markup makes it a strong value proposition for premium users.
Which One Should You Pick
Choose the HDFC Bank MoneyBack Plus Credit Card ⓘ if you are a first-time credit card user or someone whose spending is primarily online shopping and who prefers a straightforward cashback rewards system. It is well suited for budget-conscious users willing to spend enough to waive the annual fee but who do not require travel or lounge benefits. Skip this card if you travel abroad frequently or want premium perks.
The Standard Chartered Priority Visa Infinite Credit Card ⓘ is ideal for premium customers who value travel benefits, including unlimited domestic lounge access and multiple international lounge entries. It suits Priority Banking relationship holders who want a lifetime free card with higher base rewards and lower forex markup. Avoid this card if you do not qualify for Priority Banking or if you prefer a very simple cashback system without travel perks.
Overall, if you qualify and seek travel and premium rewards with no fees, the Standard Chartered Priority Visa Infinite ⓘ is the superior choice. For entry-level users focusing on online cashback and shopping, the HDFC MoneyBack Plus ⓘ remains a solid, low-cost option.
What to Check Before You Apply
- Confirm the monthly spend requirement to waive the HDFC MoneyBack Plus annual fee, as falling short means paying Rs 500 annually.
- Understand that the points reward system means redemption values can vary; check how points convert before assuming rupee equivalence.
- Note the high forex markup of 3.5% on the MoneyBack Plus card versus 2% on Standard Chartered, affecting foreign transactions.
- Verify the lounge access details and whether you meet any eligibility criteria, especially for Standard Chartered’s Priority card lounges.

Comments
No comments yet
Be the first to share your experience with this card.