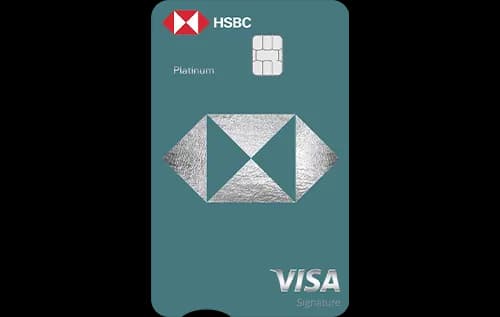
Quick Verdict
- The HSBC Visa Platinum Credit Card ⓘ wins for everyday spend with a higher base reward rate of 0.67% compared to 0.25% on the BPCL SBI Credit Card ⓘ.
- For fuel expenses, the BPCL SBI Credit Card ⓘ clearly wins with a rewarding 4.25% back, far surpassing HSBC’s no special fuel category.
- HSBC’s card is free for life, making it cheaper to hold, while BPCL SBI charges Rs 499 annually but offers a fee waiver on Rs 1,00,000 spend.
- Pick HSBC Visa Platinum for dining, shopping, and a lifetime free card suitable for first-timers. Choose BPCL SBI if you spend heavily on fuel and can meet the fee waiver threshold.
Side by Side
| Detail | HSBC Visa Platinum Credit Card ⓘ | BPCL SBI Credit Card ⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 1,00,000 annually | |
| Reward rate | 0.67% base, 2% dining | 0.25% base, 4.25% fuel, 1.25% online |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | lifetime-free, first-card, dining, shopping | fuel, first-card |
Rewards Compared
On a Rs 10,000 spend, the HSBC Visa Platinum Credit Card ⓘ returns Rs 67 in rewards at the base rate. Its standout category is dining, where it returns Rs 200 on the same spend, nearly triple the base rate, making it a good choice for food lovers and casual shoppers. The rewards are points-based but the effective return is clearly stated, simplifying value assessment.
The BPCL SBI Credit Card ⓘ has a lower base return of Rs 25 on Rs 10,000 spend, less than half that of HSBC’s card. However, it shines in the fuel category, offering Rs 425 back on Rs 10,000 spent on fuel, which is a significant upside for car owners or those with heavy fuel expenses. Its online spend category offers Rs 125 back, better than base but not as strong as fuel. For general spend, BPCL SBI is weaker, but it rewards specialized spending well.
Fees Compared
The HSBC Visa Platinum Credit Card ⓘ is a standout with no joining or annual fees, making it a zero-cost card to keep, regardless of spend. This suits those who want a first card or a no-hassle option.
The BPCL SBI Credit Card ⓘ charges Rs 499 for joining and the same amount annually. However, the annual fee is waived if you spend Rs 1,00,000 per year, which breaks down to about Rs 8,333 per month. To cover the annual fee purely from base rewards, you would need to spend nearly Rs 2,00,000 annually at the base rate, which is quite high. The fee waiver threshold is reasonable for fuel-heavy users but can be a barrier for others.
Which One Should You Pick
Choose the HSBC Visa Platinum Credit Card ⓘ if you want a card that is free for life, offers decent rewards on everyday spend, and especially if you enjoy dining out or shopping. It suits first-time cardholders and those who dislike complicated fee waiver conditions. However, skip it if you want rewards on fuel or international lounge access.
Opt for the BPCL SBI Credit Card ⓘ if you have significant fuel expenses and can meet the Rs 1,00,000 annual spend to waive the fees. It suits drivers and fuel spenders who want to maximize returns in that category. Avoid it if you do not spend enough to waive the fee or if you want rewards in broader categories like dining or shopping.
Overall, HSBC Visa Platinum Credit Card ⓘ is the better everyday card for most consumers due to its zero fees and better base rate, while BPCL SBI Credit Card ⓘ is a niche card that rewards fuel spenders well but at a cost.
What to Check Before You Apply
- Confirm if the fuel category rewards on BPCL SBI cover all fuel types or only BPCL outlets.
- Check redemption options and value for points on both cards to ensure you get the best from rewards.
- Understand the fee waiver maths on BPCL SBI carefully; monthly spend needs to average Rs 8,333 to avoid the annual fee.
- Remember both cards charge a 3.5% forex markup, so they are costly for international transactions.
- Neither card offers domestic or international lounge access, so do not expect travel perks.

Comments
No comments yet
Be the first to share your experience with this card.