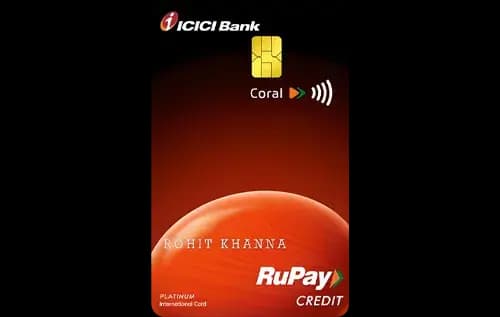
Quick Verdict
- For everyday spending, the IndusInd Platinum AUra Edge Credit Cardⓘ offers better returns, especially on dining, grocery, and online categories.
- The ICICI Bank Coral Credit Cardⓘ wins if you value domestic lounge access, offering 4 complimentary visits per year.
- The IndusInd card is cheaper to hold with no joining or annual fees, making it ideal for fee-sensitive users.
- Choose ICICI Coral if you prioritize lounge benefits and occasional utility or grocery rewards; pick IndusInd Platinum AUra Edge for a fee-free card with strong category rewards on shopping and dining.
Side by Side
| Detail | ICICI Bank Coral Credit Cardⓘ | IndusInd Platinum AUra Edge Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 0.5% base | 0.7% base |
| Reward type | points | points |
| Domestic lounge | 4 per year | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, rewards, dining, lounge | lifetime-free, rewards, first-card, shopping |
Rewards Compared
The ICICI Bank Coral Credit Cardⓘ provides a base return of Rs 50 per Rs 10,000 spent, which increases to Rs 100 in grocery and utilities categories due to a 1.0% effective reward rate. This makes it a modest choice for regular spends, especially if you shop often for groceries or pay utility bills with the card.
In contrast, the IndusInd Platinum AUra Edge Credit Cardⓘ delivers Rs 70 back on every Rs 10,000 spent across general expenses, with impressive category returns of Rs 210 on dining, grocery, and online spending thanks to a 2.1% reward rate in these segments. This makes it a strong card for shoppers and diners seeking enhanced cashback without any fee burden.
Fees Compared
The ICICI Coral card charges Rs 500 as both joining and annual fees, which can be waived if you spend Rs 1.50 lakh annually, equivalent to Rs 12,500 monthly. To justify this fee purely through rewards at the base rate, you need to spend roughly Rs 1.00 lakh in a year. The IndusInd Platinum AUra Edge card has no joining or annual fees and no waiver conditions, making it cost-free to hold indefinitely. For spenders who cannot meet the Coral’s fee waiver threshold, the IndusInd card is financially advantageous.
Which One Should You Pick
The ICICI Bank Coral Credit Cardⓘ is best for users who want domestic lounge access and a decent rewards program on utilities and grocery spends. First-time cardholders who value lounges and occasional dining rewards may find this card suitable. However, if you rarely use lounges or do not meet the fee waiver spend, this card might not be cost-effective.
The IndusInd Platinum AUra Edge Credit Cardⓘ suits spenders looking for a lifetime free card with strong rewards on dining, grocery, and online shopping. This is ideal for users who want to maximize returns without worrying about fees or spending thresholds. Avoid this card if you prioritize lounge access or utility bill rewards, which it does not offer.
Overall, if you want fuss-free, higher category rewards and no fees, go with the IndusInd Platinum AUra Edge Credit Cardⓘ. If lounge visits and utility rewards are important, and you can meet the fee waiver, the ICICI Coral Credit Cardⓘ is preferable.
What to Check Before You Apply
- Verify the quarterly Rs 75,000 spend gate for domestic lounge access on the ICICI Coral card.
- Understand the actual redemption value of points, as the rate is expressed in effective return percentage, not raw points.
- Calculate if you can meet the Rs 12,500 monthly spend to waive ICICI Coral’s annual fee.
- Both cards apply a 3.5% forex markup, so consider if you frequently travel abroad or spend in foreign currency.
- Check if the domestic lounges available on the Coral card suit your travel routes and preferences.

Comments
No comments yet
Be the first to share your experience with this card.