Quick Verdict
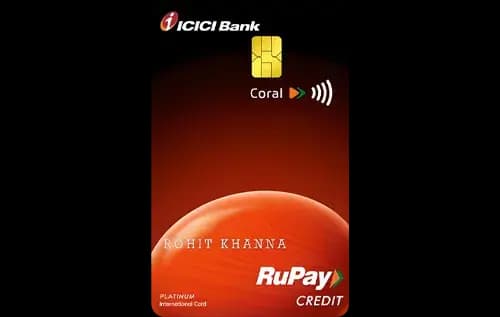
- For everyday spending including groceries and utilities, the ICICI Bank Coral Credit Cardⓘ is decent but offers modest rewards. The Standard Chartered Priority Visa Infinite Credit Cardⓘ delivers higher returns and is the clear winner.
- When it comes to travel perks and lounge access, Standard Chartered’s card provides unlimited domestic lounge visits and six international lounge visits annually, making it superior for frequent travelers.
- The Standard Chartered card is cheaper to hold with no joining or annual fees, while the ICICI Coral card charges Rs 500 for both but offers fee waivers on Rs 1.50 lakh annual spend.
- Choose ICICI Coral if you want a simple starter card focusing on dining and occasional lounge access. Pick Standard Chartered Priority Infinite if you want premium rewards, travel benefits, and lifetime free fees.
Side by Side
| Detail | ICICI Bank Coral Credit Cardⓘ | Standard Chartered Priority Visa Infinite Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh annually (Rs 12,500 monthly) | None |
| Reward rate | 0.5% base; 1% on grocery and utilities | 1% base; 2% on online and travel |
| Reward type | Points | Points |
| Domestic lounge | 4 per year (Rs 75,000 quarterly spend gate) | Unlimited |
| International lounge | None | 6 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | First card, rewards, dining, lounge | Premium, lounge, travel, lifetime free, shopping |
Rewards Compared
On a Rs 10,000 spend, the ICICI Bank Coral Credit Cardⓘ returns Rs 50 at its base rate. If your spend is in grocery or utilities categories, this rises to Rs 100 per Rs 10,000, doubling the base reward rate. This makes it moderately rewarding for everyday essentials and utilities but limited beyond these categories.
In contrast, the Standard Chartered Priority Visa Infinite Credit Cardⓘ yields Rs 100 on a base Rs 10,000 spend, twice that of the Coral’s base. For online shopping and travel spends, the rewards double again to Rs 200 per Rs 10,000, which is four times the Coral’s base rewards. This card is clearly designed for premium and frequent spenders in travel and online categories, providing much higher effective returns.
Fees Compared
The ICICI Coral card charges Rs 500 each for joining and annual fees. However, the annual fee is waived if you spend Rs 1.50 lakh annually or Rs 12,500 every month. This threshold is fairly high for casual users but achievable for regular spenders. The break-even spend to cover the annual fee through base rewards alone is about Rs 1.00 lakh per year.
The Standard Chartered Priority Visa Infinite card has no joining or annual fees, making it attractive for those wanting to avoid recurring charges. There is no waiver threshold since fees are nil throughout. For users concerned about cost of holding, Standard Chartered’s card is more economical especially if your spend is below Coral’s waiver limit.
Which One Should You Pick
Choose the ICICI Bank Coral Credit Cardⓘ if you are a first-time credit card user looking for modest rewards on groceries, utilities, and dining with a few lounge visits domestically. This card suits those who want to build credit, enjoy occasional lounge access, and are comfortable meeting the Rs 1.50 lakh annual spend for fee waivers. Skip this if you travel internationally often or want strong rewards on broader categories.
Opt for the Standard Chartered Priority Visa Infinite Credit Cardⓘ if you are a premium spender who values travel perks, unlimited domestic lounges, and international lounge access. Its higher rewards on travel and online spending, coupled with zero fees, make it ideal for frequent travelers and shoppers with a Priority Banking relationship. Avoid this card if you do not have Priority Banking or if your spend is minimal, as it requires such a relationship for welcome benefits.
Overall, for 2026, the Standard Chartered Priority Visa Infinite card wins for rewards, travel benefits, and cost-effectiveness. ICICI Coral remains a solid starter card but cannot match the premium perks and reward rates of Standard Chartered.
What to Check Before You Apply
- Verify the exact quarterly spend gate of Rs 75,000 for domestic lounge access on ICICI Coral to ensure you can meet it.
- Check redemption options and point expiry rules for both cards to avoid losing rewards.
- Confirm your ability to meet ICICI Coral’s Rs 1.50 lakh annual spend for fee waiver to avoid paying Rs 500 annually.
- For foreign travel, remember ICICI Coral charges 3.5% forex markup compared to 2% on Standard Chartered Priority Infinite.

Comments
No comments yet
Be the first to share your experience with this card.