Quick Verdict
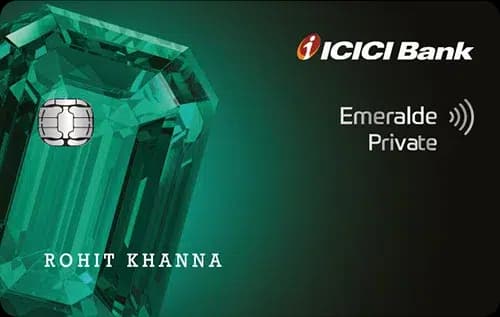
- The ICICI Bank Emeralde Private Metal Credit Cardⓘ wins for everyday spend with its higher 3% base reward rate.
- For travel and lounge access, the ICICI card also leads with unlimited international lounge visits and a strong travel reward rate.
- The SBI AURUM Credit Cardⓘ is cheaper to hold, with a Rs 2,500 lower annual fee and a marginally better forex markup.
- Pick the ICICI Emeralde if you prioritize premium travel benefits and higher rewards on diverse categories; choose SBI AURUM if you want a lower fee card with decent dining and grocery rewards.
Side by Side
| Detail | ICICI Bank Emeralde Private Metal Credit Card | SBI AURUM Credit Card |
|---|---|---|
| Annual fee | Rs 12,499 | Rs 9,999 |
| Joining fee | Rs 12,499 | Rs 9,999 |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 3% base, 3% on online, dining, travel | 1% base, 2.5% on dining, grocery |
| Reward type | points | points |
| Domestic lounge | Unlimited | Unlimited |
| International lounge | Unlimited | 6 per year |
| Forex markup | 2% | 1.99% |
| Best suited for | premium, travel, lounge, rewards, forex, shopping | premium, lounge, rewards, dining, travel, shopping |
Rewards Compared
The ICICI Bank Emeralde Private Metal Credit Cardⓘ offers a straightforward 3% reward rate on all spends including online, dining, and travel categories. On Rs 10,000 of spend, this translates to Rs 300 back in rewards, making it a highly rewarding option for premium users who spend across these categories. This uniform rate simplifies rewards earning and boosts returns on lifestyle and travel spends.
In contrast, the SBI AURUM Credit Cardⓘ provides a base reward rate of 1%, which yields Rs 100 on Rs 10,000 spend. However, it enhances rewards to 2.5% on dining and grocery categories, giving Rs 250 back on Rs 10,000 spent there. This makes it a better choice for cardholders who primarily spend on dining and groceries but less rewarding overall compared to the ICICI card’s broad 3% rate.
Fees Compared
The ICICI Emeralde card commands a higher joining and annual fee of Rs 12,499 each, compared to Rs 9,999 for the SBI AURUM. This Rs 2,500 fee premium demands higher spend to justify the value. The ICICI card’s break-even point for fee recovery at base rewards alone is about Rs 4.17 lakh annually, whereas the SBI AURUM requires nearly Rs 10 lakh spend to cover its fee via base rewards.
Neither card specifies fee waiver thresholds based on annual spend, so cardholders should consider the fee as a fixed cost. The ICICI card’s higher rewards rate means the extra Rs 2,500 fee can be recovered with an additional Rs 1.25 lakh in spend compared to SBI AURUM, assuming consistent category rewards.
Which One Should You Pick
Choose the ICICI Bank Emeralde Private Metal Credit Cardⓘ if you are a premium spender focused on travel, dining, and online shopping who values unlimited lounge access and concierge services. The 3% rewards rate across all major categories and the complimentary Taj Epicure and EazyDiner memberships add significant lifestyle value. However, skip this card if your annual spend is below Rs 4.17 lakh as the high fees may not be justified.
The SBI AURUM Credit Cardⓘ suits those who want a prestigious card with good dining and grocery rewards, plus a slightly better forex markup at 1.99%. It also offers premium benefits like choice of Club Marriott or Taj Epicure memberships and six international lounge visits annually. This card is a better fit if you prefer a lower fee and spend more selectively in dining and groceries. Avoid this card if you want higher rewards on travel or online spends, as its base rate is only 1%.
Overall, the ICICI Emeralde card wins for comprehensive rewards and travel benefits, while SBI AURUM appeals to selective spenders seeking value in dining and grocery categories with a lower fee commitment.
What to Check Before You Apply
- Confirm the caps on reward points earning per category to avoid surprises in maximum returns.
- Verify the redemption value of points as it can affect the effective reward rate and card value.
- Understand the fee waiver conditions if any, and calculate if your spend justifies the annual fee.
- Check the forex markup carefully if you travel frequently, as small differences can add up on large foreign spends.
- Review the lounge access terms and participating airports to ensure availability matches your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.