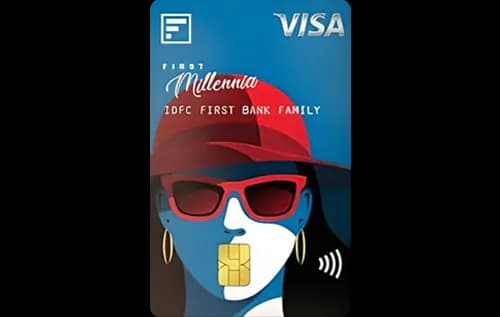
Quick Verdict
- The IndusInd Bank Tiger Credit Cardⓘ offers a better base reward rate, making it the winner for everyday spending, especially for online and UPI transactions.
- Both cards provide domestic lounge access, but the Tiger Card’s higher quarterly spend gate makes it more suitable for frequent lounge users and travel enthusiasts.
- Both cards are lifetime free with no joining or annual fees, but the Tiger Card demands a higher spend for lounge access.
- Choose the IDFC First Millennia Cardⓘ if you want a simple, no-fee card with welcome benefits and modest rewards. Opt for the Tiger Card if you prioritize rewards on online and UPI spends and want better lounge access.
Side by Side
| Detail | IDFC First Millennia Cardⓘ | IndusInd Bank Tiger Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | None | None |
| Reward rate | 0.5% | 1% base, 2.5% online, 1% UPI |
| Reward type | Points | Points |
| Domestic lounge | 4 per year, Rs 20,000 monthly spend gate | 4 per year, Rs 40,000 quarterly spend gate |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Lifetime-free, first-card, shopping | Lifetime-free, UPI-Rupay, rewards, lounge, travel |
| Golf access | No | Yes |
Rewards Compared
The IDFC First Millennia Cardⓘ delivers Rs 50 back on Rs 10,000 spent, reflecting its base reward rate of 0.5%. This modest return suits those looking for a no-fee card with straightforward benefits and a welcome offer that includes 5% cashback on first EMI spends up to Rs 1,000 plus vouchers worth Rs 500 on spending Rs 5,000 within 30 days. Its rewards are simple but limited in scope, focusing on general shopping rather than specific categories.
In contrast, the IndusInd Bank Tiger Credit Cardⓘ doubles this base return to Rs 100 per Rs 10,000 spent and significantly boosts rewards to Rs 250 per Rs 10,000 on online spends. It also offers a 1% return on UPI transactions, making it much more rewarding for digital payments and e-commerce. This makes it a better pick for tech-savvy users who spend heavily online or use UPI frequently. The Tiger Card’s reward structure is clearly tilted towards digital and travel-related spends, aligning with its travel and lounge benefits.
Fees Compared
Both cards have no joining or annual fees, making them attractive for users who dislike fee burdens. The IDFC First Millennia Cardⓘ is truly fee-free for life, with no waiver thresholds since no fees apply. The IndusInd Bank Tiger Credit Cardⓘ is similarly free but requires a higher spend gate for domestic lounge access: Rs 40,000 quarterly, compared to Rs 20,000 monthly for the Millennia Card. This means Tiger Card holders need to spend more to access lounges without extra charges.
The break-even for lounge cost based on spend gates favors the Millennia Card for more frequent, lower-spend lounge visits, while Tiger Card suits those with larger quarterly spends who want lounge access and golf privileges. Both cards charge a 3.5% forex markup, which is standard for Indian credit cards.
Which One Should You Pick
Choose the IDFC First Millennia Cardⓘ if you want a straightforward, lifetime-free card with modest rewards and welcome bonuses. It is ideal for first-time card users or those who prefer shopping rewards and occasional domestic lounge visits without worrying about high spend thresholds. Avoid this card if you do a lot of online or UPI transactions and are looking for higher returns.
Go for the IndusInd Bank Tiger Credit Cardⓘ if you are a frequent online shopper or UPI user who wants better rewards and are comfortable meeting a higher spend gate for lounges. It suits travelers who value golf access and lounge privileges without an annual fee. Skip this card if you spend less frequently or are not interested in lounge or golf benefits, as the higher spend gate may be restrictive.
Overall, the Tiger Card edges out for reward seekers and travelers, while the Millennia Card wins on simplicity and shopping focus.
What to Check Before You Apply
- Confirm the monthly or quarterly spend gates carefully to ensure you qualify for lounge access.
- Understand the redemption value of points since both cards use a points system with different effective returns.
- Review the waiver math to avoid unexpected fees if your spending fluctuates.
- Consider the 3.5% forex markup cost if you plan to use the card extensively abroad.
- Check which domestic airports the lounge access covers and if the number of entries suits your travel frequency.

Comments
No comments yet
Be the first to share your experience with this card.