Quick Verdict
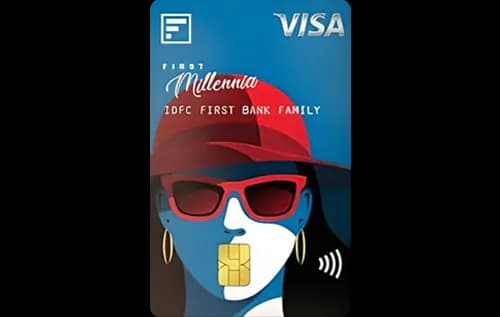
- The IDFC First Millennia Cardⓘ offers a higher base reward rate, making it better for everyday spend outside specific categories.
- The RBL Bank ShopRite Credit Cardⓘ excels in grocery and fuel spends with a 5% reward rate.
- Both cards are lifetime free with no joining or annual fees, but RBL Bank ShopRite requires Rs 2 lakh annual spend for fee waiver, effectively making it free.
- Pick the IDFC First Millennia for a no-frills, lifetime-free card with decent rewards and domestic lounge access; choose RBL ShopRite if your spending heavily leans towards groceries and fuel.
Side by Side
| Detail | IDFC First Millennia Cardⓘ | RBL Bank ShopRite Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | Rs 2.00 lakh annual (Rs 16,667 monthly) | |
| Reward rate | 0.5% base | 0.4% base, 5% grocery, 5% fuel |
| Reward type | Points | Points |
| Domestic lounge | 4 per year (Rs 20,000 monthly spend gate) | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Lifetime-free, first-card, shopping | Cashback, grocery, fuel, shopping |
Rewards Compared
On a Rs 10,000 spend outside of special categories, the IDFC First Millennia Cardⓘ earns Rs 50 worth of points, reflecting its 0.5% base reward rate. This makes it a straightforward choice for general spending where no category bonuses apply. Its base rate is the higher of the two cards in this comparison.
By contrast, the RBL Bank ShopRite Credit Cardⓘ offers Rs 40 per Rs 10,000 spent on general categories at 0.4%. However, it significantly boosts rewards in groceries and fuel to 5%, equating to Rs 500 back on Rs 10,000 spent in each category. This makes RBL ShopRite a powerful card for those whose expenses are concentrated in these areas, delivering tenfold the base reward rate.
Fees Compared
Neither card charges a joining or annual fee, making them attractive for cost-conscious users. The IDFC First Millennia Card is truly lifetime free with no fee waiver conditions, ideal for low or irregular spenders.
The RBL Bank ShopRite Credit Card also advertises no joining or annual fee but mandates Rs 2 lakh annual spend to waive fees. This translates to Rs 16,667 monthly spend needed to avoid fees, which could be a barrier for moderate spenders. If you meet this threshold, the card is effectively free and rewards heavily in grocery and fuel categories.
Which One Should You Pick
The IDFC First Millennia Cardⓘ is best suited for first-time credit card users or those seeking a simple, lifetime-free card with a decent base reward rate and occasional domestic lounge access. It is ideal for general shopping and users who do not want to worry about fee waivers or high monthly spend targets. Skip this card if you prioritize high category rewards over flexibility.
The RBL Bank ShopRite Credit Cardⓘ caters well to users with consistent, high monthly spends in groceries and fuel, as its 5% rewards in these categories are compelling. It is also good for shoppers seeking cashbacks without an upfront fee. However, if you do not regularly spend Rs 16,667 monthly or dislike spending to waive fees, this card may not be economical. Avoid this card if your spend pattern is diverse or low.
The final call: for no-hassle, lifetime-free credit with reasonable rewards and some lounge benefits, go with the IDFC First Millennia Cardⓘ. For category-focused, high-value rewards in grocery and fuel with a spend commitment, the RBL Bank ShopRite Credit Cardⓘ wins.
What to Check Before You Apply
- Confirm any caps or limits on category rewards, especially for grocery and fuel spends on RBL ShopRite.
- Evaluate the redemption process and value of points earned, as both cards provide points but details on conversion and usage may differ.
- Understand the exact fee waiver math for the RBL ShopRite card to avoid unexpected fees if monthly spend dips below Rs 16,667.
- Both cards have a 3.5% forex markup; consider this cost if you intend to use the cards abroad.
- Check the domestic lounge access rules on the IDFC First Millennia Card, particularly the Rs 20,000 monthly spend gate for lounge visits.

Comments
No comments yet
Be the first to share your experience with this card.