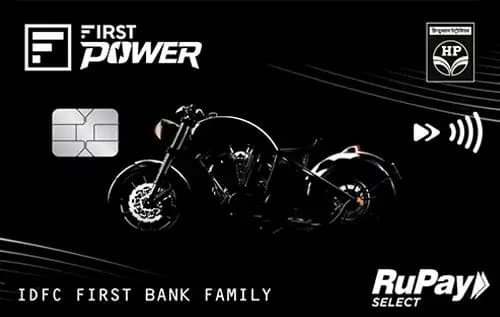
Quick Verdict
- The IDFC HPCL First Power Credit Card ⓘ wins for everyday spending, especially on fuel, groceries, and utilities, thanks to its higher category reward rates.
- Neither card offers lounge access, so neither wins on travel perks or lounges.
- The IDFC card is cheaper to hold if you can meet its lower waiver spend of Rs 50,000 annually compared to Rs 1.00 lakh for the BPCL SBI Credit Card ⓘ.
- Choose the IDFC HPCL First Power Credit Card ⓘ if you want better rewards on essential spends with a low fee waiver. Opt for the BPCL SBI Credit Card ⓘ if you prefer the SBI network and can justify the higher fee with your spend.
Side by Side
| Detail | IDFC HPCL First Power Credit Card ⓘ | BPCL SBI Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 199 | Rs 499 |
| Joining fee | Rs 199 | Rs 499 |
| Fee waiver on spend | Rs 50,000 | Rs 1.00 lakh |
| Reward rate | 0.75% base, 5% fuel, grocery, utilities | 0.25% base, 4.25% fuel, 1.25% online |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, upi-rupay, first-card | fuel, first-card |
Rewards Compared
The IDFC HPCL First Power Credit Card ⓘ offers a base reward rate of 0.75%, which translates to Rs 75 back on Rs 10,000 spent. This base rate is already three times higher than the BPCL SBI Credit Card ⓘ, which offers a 0.25% base rate, or Rs 25 back on the same spend. Where the IDFC card really shines is in its category spends: it gives 5% rewards on fuel, grocery, and utilities, equating to Rs 500 back per Rs 10,000 spent in each category. This makes it a strong choice for everyday essential expenses.
Conversely, the BPCL SBI Credit Card ⓘ offers 4.25% rewards on fuel spends, returning Rs 425 on Rs 10,000, which is slightly lower than the IDFC card’s fuel category. For online transactions, it offers a modest 1.25% rewards rate or Rs 125 back on Rs 10,000. The rest of the spends earn the base 0.25% reward rate. Thus, while the BPCL SBI card provides some value in fuel spending, it falls short on broader categories compared to the IDFC HPCL First Power Credit Card ⓘ.
Fees Compared
The IDFC HPCL First Power Credit Card ⓘ has a joining fee and annual fee of Rs 199 each, which is significantly lower than the BPCL SBI Credit Card ⓘ fees of Rs 499 for both joining and annual fees. The IDFC card offers a fee waiver with a relatively low annual spend requirement of Rs 50,000, or about Rs 4,167 per month. On the other hand, the BPCL SBI Credit Card ⓘ requires double that annual spend, Rs 1.00 lakh or about Rs 8,333 monthly, to waive the fees.
When considering break-even spends to cover the fee through base rewards, the IDFC HPCL First Power Credit Card ⓘ requires Rs 26,533 of spend at the base rate, while the BPCL SBI Credit Card ⓘ needs a much higher Rs 1,99,600, roughly Rs 2.00 lakh, given its lower base reward rate. This means the IDFC card is more cost-effective for users with moderate spending, while the BPCL card demands much higher spend to justify the fees.
Which One Should You Pick
The IDFC HPCL First Power Credit Card ⓘ is ideal for users who want strong rewards on everyday essential categories such as fuel, groceries, and utilities. Its low joining and annual fees combined with a low fee waiver threshold make it a sensible choice for moderate spenders who want good returns without worrying about high fee recovery. It also suits first-time credit card users and those who prefer UPI-RuPay spending benefits.
The BPCL SBI Credit Card ⓘ caters better to those who are loyal to the SBI Card network and who spend heavily on fuel and online shopping, although the online rewards are modest. It may appeal to users who can comfortably meet the higher fee waiver threshold and thus avoid the higher fees. However, due to its lower base and category returns, it is less attractive for moderate spenders.
Overall, the IDFC HPCL First Power Credit Card ⓘ is the better pick for most users in 2026, especially those focused on maximizing rewards on everyday spends at a low cost. The BPCL SBI Credit Card ⓘ should be skipped by anyone with average monthly spend below Rs 8,333 or who wants broader category benefits. The IDFC card is less suitable if you rarely spend on fuel or utilities and want travel perks, which neither card offers.
What to Check Before You Apply
- Check if the high category reward rates on the IDFC card have any caps or limits per billing cycle to avoid overestimating rewards.
- Understand the redemption value of points for each card, as point conversions can vary and affect the effective reward rate.
- Carefully calculate the monthly spend needed to waive the fees; if you cannot meet the threshold, the fees may outweigh the benefits.
- Both cards charge a 3.5% forex markup. Avoid using these cards for foreign currency spends if you want to save on forex charges.
- Neither card offers domestic or international lounge access; travelers looking for lounge benefits should consider other options.

Comments
No comments yet
Be the first to share your experience with this card.