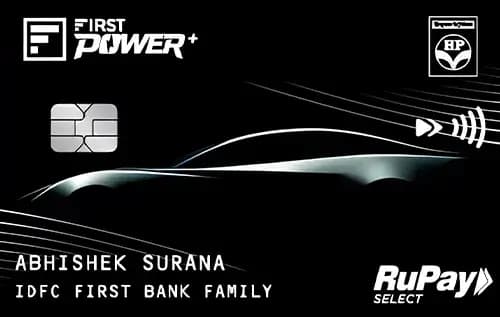
Quick Verdict
- The IDFC HPCL First Power Plus Credit Cardⓘ wins for everyday spending with a higher base reward rate and stronger category returns on fuel, grocery, and utilities.
- For travel or lounge access, the IDFC HPCL card also leads with 4 complimentary domestic lounge visits annually, whereas the BPCL SBI Credit Card offers none.
- Both cards have an identical joining and annual fee of Rs 499, but the IDFC card’s fee waiver threshold is higher at Rs 1.50 lakh annual spend compared to Rs 1.00 lakh for the BPCL SBI card.
- Choose the IDFC HPCL First Power Plus if you spend heavily on fuel and groceries and value lounge access. Opt for the BPCL SBI Credit Card if you want a simple fuel-focused card with a lower fee waiver limit and are a first-time cardholder.
Side by Side
| Detail | IDFC HPCL First Power Plus Credit Card ⓘ | BPCL SBI Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 499 | Rs 499 |
| Joining fee | Rs 499 | Rs 499 |
| Fee waiver on spend | Rs 1.50 lakh | Rs 1.00 lakh |
| Reward rate | 0.75% base | 0.25% base |
| Reward type | Points | Points |
| Domestic lounge | 4 per year (Rs 20,000 monthly spend gate) | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Fuel, UPI-RuPay, Grocery, Lounge | Fuel, First card |
Rewards Compared
On a Rs 10,000 spend, the IDFC HPCL First Power Plus Credit Cardⓘ delivers Rs 75 back at its base rate and significantly more in its key categories: Rs 650 on fuel, Rs 500 on groceries, and Rs 500 on utilities. This makes it a rewarding choice for users with diverse spending habits who want to maximize returns in everyday categories. The card’s welcome benefit includes a Rs 500 gift voucher on the first HPCL fuel transaction and up to 5% cashback on the first EMI, further sweetening the deal.
In contrast, the BPCL SBI Credit Cardⓘ offers a modest Rs 25 back on a Rs 10,000 base spend but raises the rate to Rs 425 on fuel and Rs 125 on online spends. This card’s reward structure is more narrowly focused, favoring fuel purchases and online transactions but with a lower overall return rate. The welcome benefit of 2,000 reward points worth Rs 500 provides a decent initial bonus for new cardholders.
Fees Compared
Both cards charge a joining and annual fee of Rs 499. The IDFC HPCL First Power Plus requires an annual spend of Rs 1.50 lakh (approximately Rs 12,500 per month) to waive the fee, which is a higher bar compared to the BPCL SBI Credit Card’s Rs 1.00 lakh (around Rs 8,333 monthly). This means frequent spenders or those with high fuel and grocery bills will find it easier to waive the fee on the BPCL SBI card.
The IDFC HPCL card’s break-even spend to cover the annual fee at the base rate stands at Rs 66,533, reflecting its higher reward rate. The BPCL SBI Credit Card requires nearly Rs 2.00 lakh in spend to break even at the base level, indicating less value for light spenders. Both cards have the standard 3.5% forex markup on foreign currency transactions, making them less attractive for frequent international travelers unless they primarily benefit from domestic rewards and lounges.
Which One Should You Pick
The IDFC HPCL First Power Plus Credit Cardⓘ suits customers who have a consistent and sizeable monthly spend on fuel, groceries, and utilities, and who value domestic lounge access. Its higher rewards on key categories and lounge benefits justify the higher fee waiver threshold. Buyers who want a robust card for multiple daily spends with lounge perks should pick this card. Skip this card if your spend is below Rs 12,500 monthly or if you rarely use lounges.
The BPCL SBI Credit Cardⓘ is ideal for first-time credit card users looking for a simple and affordable fuel-focused rewards card. Its lower fee waiver limit makes it accessible for moderate spenders who want to save on fees without chasing high category rewards. Opt for this card if your spending is mostly on fuel and you prefer a straightforward rewards structure. Avoid it if you want better rewards on groceries or lounge access.
Overall, the IDFC HPCL First Power Plus Credit Card provides more comprehensive rewards and benefits for diverse spenders and lounge users, making it the stronger pick for most customers. The BPCL SBI Credit Card is a decent entry-level option for fuel-centric spenders with moderate spend capacity.
What to Check Before You Apply
- Confirm the monthly spend gates for lounge access on the IDFC HPCL card, as only Rs 20,000 monthly spend qualifies.
- Understand the redemption value of points since both cards use points as a reward type and valuation may vary.
- Calculate your expected annual spend to realistically assess if you can meet the fee waiver thresholds of Rs 1.50 lakh or Rs 1.00 lakh.
- Be aware of the 3.5% forex markup on both cards, which can add significant cost to foreign transactions.
- Check the availability and location of domestic lounges accessible with the IDFC HPCL card to ensure they align with your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.