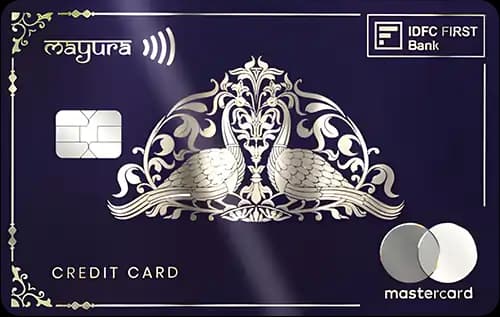
Quick Verdict
- The Mayura Credit Cardⓘ offers the highest reward rate for everyday spends at 1.5% base and 3% on dining, travel, and online categories.
- For travel and lounge benefits, the Marriott Bonvoy HDFC Bank Credit Cardⓘ is superior with 12 domestic and international lounge visits annually and complimentary Marriott Silver Elite status.
- The Marriott Bonvoy card is cheaper to hold with a Rs 3,000 annual fee versus Rs 5,999 on the Mayura card.
- Choose Mayura for premium rewards and forex savings. Opt for Marriott Bonvoy if you value lounge access, hotel status, and lower fees.
Side by Side
| Detail | Mayura Credit Cardⓘ | Marriott Bonvoy HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 5,999 | Rs 3,000 |
| Joining fee | Rs 5,999 | Rs 3,000 |
| Fee waiver on spend | None | None |
| Reward rate | 1.5% base; 3% on dining, travel, online | 1.3% base; 2.6% on travel and dining |
| Reward type | Points | Points |
| Domestic lounge | Unlimited | 12 per year |
| International lounge | 8 per year | 12 per year |
| Forex markup | 1.5% | 3.5% |
| Best suited for | Premium, travel, lounge, rewards, forex, shopping | Travel, premium, lounge, rewards, shopping |
| Golf access | Yes | Yes |
| Concierge service | No | Yes |
Rewards Compared
Spending Rs 10,000 on the Mayura Credit Cardⓘ earns Rs 150 back at the base rate. When spending is focused on dining, travel, or online shopping, the reward rate triples to 3%, translating to Rs 300 back on Rs 10,000 spent in those categories. This makes the Mayura card particularly rewarding for lifestyle and travel-related expenses.
On the other hand, the Marriott Bonvoy HDFC Bank Credit Cardⓘ offers Rs 130 back on Rs 10,000 at the base rate. For travel and dining spends, the return improves to 2.6%, yielding Rs 260 on Rs 10,000. While the rewards are slightly lower than Mayura’s category rates, the Marriott Bonvoy card’s value proposition lies in its hotel loyalty benefits and lounge access, adding indirect value beyond rewards.
Fees Compared
The Mayura Credit Cardⓘ commands a higher joining and annual fee at Rs 5,999 each, with no fee waiver linked to spend. To cover this annual fee purely through base rate rewards, a cardholder must spend approximately Rs 3,99,933 annually.
In comparison, the Marriott Bonvoy HDFC Bank Credit Cardⓘ has a lower joining and annual fee of Rs 3,000 each, also without a fee waiver. The break-even spend to cover its fee at base rate is about Rs 2,30,769 per year.
The Mayura card’s higher reward rate justifies its higher fee only if the cardholder’s spend exceeds Rs 14,99,500 annually compared to Marriott Bonvoy, making it practical only for very high spenders. For moderate spenders, Marriott Bonvoy is more cost-effective.
Which One Should You Pick
If you are a high-spending premium user who prioritizes superior reward rates on dining, travel, and online spends, and you frequently transact in foreign currency, the Mayura Credit Cardⓘ suits you best. Its low forex markup of 1.5% also makes it ideal for overseas spenders. However, avoid this card if your annual spend is below Rs 4 lakh as you may not justify the high fees.
The Marriott Bonvoy HDFC Bank Credit Cardⓘ is tailored for travelers who value airport lounge access and Marriott Bonvoy program benefits like Silver Elite status and free night awards. Its lower fees and concierge services add to its appeal for frequent hotel guests and those preferring a balanced rewards and benefits mix. Skip this card if you rarely travel or spend in its enhanced categories, as reward rates are modest.
Overall, choose Mayura for rewards-centric premium spenders and Marriott Bonvoy for travel enthusiasts looking for perks and lower cost of ownership.
What to Check Before You Apply
- Confirm if the unlimited domestic lounge access on Mayura has any blackout dates or specific lounges excluded.
- Check the redemption value of reward points on both cards, as points may vary in usefulness.
- Verify the feasibility of meeting fee waiver thresholds if any are offered, as neither card currently provides waivers.
- Review the forex markup charges carefully, especially if you spend significantly abroad, since Marriott Bonvoy’s 3.5% is higher than Mayura’s 1.5%.
- Ensure the lounges offered by Marriott Bonvoy are at airports and locations you frequent to maximize benefit.

Comments
No comments yet
Be the first to share your experience with this card.