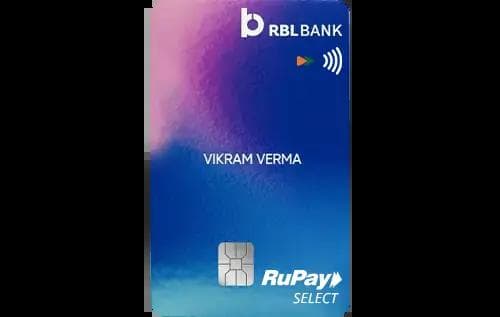
Quick Verdict
- The RBL Bank ShopRite Credit Cardⓘ wins for everyday grocery and fuel spend with a strong 5% reward rate in these categories.
- The SBI Simplyclick Credit Cardⓘ is better suited for online shopping, although its reward rate is lower at 2.5%.
- RBL’s ShopRite card is cheaper to hold with no joining or annual fees, but requires a higher spend to waive fees which is not applicable here.
- Pick RBL ShopRite if you focus on grocery and fuel spending without wanting to pay fees, and SBI Simplyclick if you are looking for an entry-level card with some online shopping benefits and can meet the lower fee waiver threshold.
Side by Side
| Detail | RBL Bank ShopRite Credit Cardⓘ | SBI Simplyclick Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 2.00 lakh | Rs 1.00 lakh |
| Reward rate | 0.4% base, 5% on grocery and fuel | 0.25% base, 2.5% on online |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | cashback, grocery, fuel, shopping | shopping, first-card |
Rewards Compared
On a Rs 10,000 spend, the RBL Bank ShopRite Credit Cardⓘ offers Rs 40 back at the base rate. However, it shines in grocery and fuel categories with Rs 500 reward value per Rs 10,000 spent. This makes it highly rewarding for users focusing on those spends. Conversely, the SBI Simplyclick Credit Cardⓘ returns Rs 25 on Rs 10,000 spent generally, but this doubles for online purchases to Rs 250 for every Rs 10,000. Hence, SBI Simplyclick is tailored for online shoppers but does not match the high category returns of RBL ShopRite.
Fees Compared
The RBL ShopRite card has no joining or annual fees, making it effectively free to hold. It does have a fee waiver condition that requires Rs 2.00 lakh annual spend to waive fees, but since fees are nil, this is irrelevant here. The SBI Simplyclick card charges Rs 499 as joining and annual fees. These can be waived with Rs 1.00 lakh annual spend, which breaks down to roughly Rs 8,333 per month. To cover the Rs 499 fee purely from rewards at base rates, one must spend about Rs 1,99,600 annually on SBI Simplyclick. Therefore, RBL ShopRite is cheaper to hold, while SBI Simplyclick requires careful spend management to justify fees.
Which One Should You Pick
Choose the RBL Bank ShopRite Credit Cardⓘ if you are a regular grocery and fuel shopper seeking high returns without worrying about fees. Its no-fee structure and elevated category rewards make it excellent for everyday essentials. However, avoid this card if your spends are mostly outside grocery and fuel or if you want lounge access and premium travel benefits.
The SBI Simplyclick Credit Cardⓘ suits first-time cardholders or those focused on online shopping who are comfortable paying a joining and annual fee that can be waived with moderate spends. It is a decent entry-level card with a welcome Amazon gift card to sweeten the deal. Skip SBI Simplyclick if you dislike annual fees or want better rewards on offline spends.
Ultimately, the RBL Bank ShopRite Credit Cardⓘ wins for category rewards and fee structure. SBI Simplyclick is a secondary choice for online spenders willing to pay fees.
What to Check Before You Apply
- Confirm if your monthly spend aligns with fee waiver thresholds: Rs 16,667 per month for RBL ShopRite, Rs 8,333 for SBI Simplyclick.
- Check reward caps or maximum points earnings on high category spends, as these can limit effective returns.
- Verify the redemption value and ease of using reward points since both cards earn points but differ in redemption options.
- Consider the 3.5% forex markup for foreign currency spend if you plan to travel or shop internationally.
- Neither card offers domestic or international lounge access, so do not expect premium travel perks.

Comments
No comments yet
Be the first to share your experience with this card.