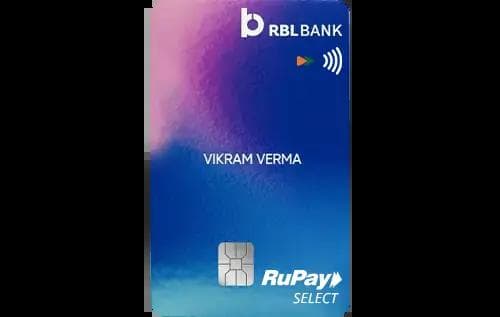
Quick Verdict
- The RBL Bank ShopRite Credit Card ⓘ wins for everyday spend with a higher base and category reward rate.
- Neither card offers domestic or international lounge access, so no advantage for travel or lounges.
- The RBL ShopRite card is cheaper to hold with no joining or annual fee, while SBI Simplysave has both fees of Rs 499.
- Choose the RBL ShopRite card if you spend heavily on grocery and fuel and want a free-to-use card; pick SBI Simplysave if you want a first credit card with modest rewards and can meet the fee waiver threshold easily.
Side by Side
| Detail | RBL Bank ShopRite Credit Card ⓘ | SBI Simplysave Credit Card ⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 2.00 lakh | Rs 1.00 lakh |
| Reward rate | 0.4% base, 5% grocery & fuel | 0.25% base, 2.5% dining & grocery |
| Reward type | Points | Points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Cashback, grocery, fuel, shopping | First card, dining, grocery, rewards, shopping |
Rewards Compared
The RBL Bank ShopRite Credit Card ⓘ delivers Rs 40 back per Rs 10,000 spent at the base reward rate, which is 60% higher than the Rs 25 per Rs 10,000 earned by the SBI Simplysave Credit Card ⓘ. In grocery and fuel categories, RBL ShopRite significantly outperforms with a 5% return or Rs 500 for every Rs 10,000 spent, compared to SBI Simplysave’s 2.5% or Rs 250 in grocery and dining categories. This makes RBL ShopRite far more attractive for users prioritizing grocery and fuel spends, while SBI Simplysave is better suited for casual dining and grocery users seeking rewards on modest spends.
Fees Compared
The RBL Bank ShopRite Credit Card ⓘ has no joining or annual fees, making it cost-effective especially for those who want a lifetime free card. However, its fee waiver threshold is Rs 2.00 lakh annually or about Rs 16,667 per month if any fee were charged. In contrast, SBI Simplysave Credit Card ⓘ charges Rs 499 as both joining and annual fees. This fee can be waived by spending Rs 1.00 lakh annually, which breaks down to Rs 8,333 monthly. The break-even spend for SBI Simplysave to cover its fee at base reward rates is approximately Rs 1,99,600, making it suitable only if you confidently spend near or above this level to justify the fees.
Which One Should You Pick
Choose the RBL Bank ShopRite Credit Card ⓘ if you prioritize high rewards on grocery and fuel expenses and want a credit card without any joining or annual fees. It suits cashback seekers and heavy grocery shoppers who want a simple no-cost card with a strong return in key categories. However, its 3.5% forex markup makes it less ideal for frequent international travellers.
Go for the SBI Simplysave Credit Card ⓘ if you are a first-time credit card user looking for moderate rewards on dining and grocery, and you are confident about meeting the Rs 1.00 lakh annual spend to waive the fees. It is a decent starter card with a straightforward rewards program and a lower fee waiver threshold compared to RBL ShopRite. That said, if you do not spend enough to waive the fee, this card could be expensive relative to the rewards earned.
In a decisive call, the RBL Bank ShopRite Credit Card ⓘ is the better pick for everyday spending and value, while SBI Simplysave Credit Card ⓘ is more for those seeking a basic entry-level card with some rewards on dining.
What to Check Before You Apply
- Confirm if your typical monthly grocery and fuel spend justifies picking the RBL ShopRite card for its 5% category rate.
- Understand that both cards have a 3.5% forex markup, making them costly for international usage.
- Calculate if your annual spend meets or exceeds the fee waiver thresholds: Rs 2.00 lakh for RBL ShopRite and Rs 1.00 lakh for SBI Simplysave.
- Neither card offers any lounge access domestically or internationally, so do not expect travel perks beyond rewards.

Comments
No comments yet
Be the first to share your experience with this card.