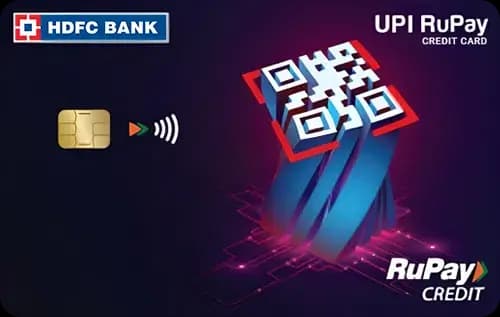
Quick Verdict
- For everyday spend, the HDFC Bank UPI Rupay Credit Card ⓘ wins with its higher cashback rates on grocery and dining.
- For travel benefits and lounge access, the Standard Chartered Easemytrip Credit Card ⓘ clearly leads thanks to its 10% cashback on travel and domestic lounge access.
- The HDFC Bank UPI Rupay card is significantly cheaper to hold with just Rs 99 annual and joining fees and no spend-based waiver conditions.
- Choose the HDFC Bank UPI Rupay card ⓘ if you want a low-cost, cashback-focused card for UPI and shopping. Opt for the Standard Chartered Easemytrip card ⓘ if you are a frequent traveler who can meet the Rs 50,000 annual spend for fee waivers and lounge access.
Side by Side
| Detail | HDFC Bank UPI Rupay Credit Card ⓘ | Standard Chartered Easemytrip Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 99 | Rs 350 |
| Joining fee | Rs 99 | Rs 350 |
| Fee waiver on spend | None | Rs 50,000 annually (Rs 4,167 per month) |
| Reward rate | 1% base, 3% grocery & dining | 1% base, 10% travel |
| Reward type | Cashback | Cashback |
| Domestic lounge | None | 4 per year (with Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | UPI-Rupay, lifetime free, shopping | Travel, first-card, lounge |
Rewards Compared
The HDFC Bank UPI Rupay Credit Card ⓘ earns Rs 100 cashback on a Rs 10,000 spend at its base 1% rate. However, it significantly rewards grocery and dining spends at 3%, giving Rs 300 cashback on Rs 10,000 spent in these categories. It also offers 1% cashback on UPI transactions. This makes it attractive for users focusing on everyday shopping and dining expenses through UPI or Rupay channels.
The Standard Chartered Easemytrip Credit Card ⓘ also gives Rs 100 cashback on a Rs 10,000 base spend but shines in the travel category with an impressive 10% cashback, translating to Rs 1,000 on Rs 10,000 spent on travel bookings. This high category rate is ideal for frequent travelers who want to maximize returns on their travel expenses. The card does not mention elevated rates for other categories, so it defaults to the 1% base cashback elsewhere.
Fees Compared
The HDFC Bank UPI Rupay Credit Card ⓘ demands a very low joining and annual fee of Rs 99 each, with no conditions for fee waivers. Its break-even spend to cover the fees at the base reward rate is Rs 9,900 annually, making it easy to justify keeping this card even with modest spend.
In contrast, the Standard Chartered Easemytrip Credit Card ⓘ charges Rs 350 for both joining and annual fees. However, these fees can be waived if the cardholder spends Rs 50,000 annually (about Rs 4,167 monthly). The break-even spend at base rewards alone is Rs 35,000, but this does not factor in the high travel category cashback, which can significantly offset costs if used strategically. For users who do not meet the waiver threshold, the card is notably more expensive to hold.
Which One Should You Pick
The HDFC Bank UPI Rupay Credit Card ⓘ is ideal for first-time cardholders and budget-conscious users who want a simple, lifetime free card with decent cashback on groceries, dining, and UPI transactions. It is best suited for everyday shopping and casual use without worrying about fee waivers or complicated rewards structures. However, it lacks any lounge access or travel perks.
The Standard Chartered Easemytrip Credit Card ⓘ fits frequent travelers who can take advantage of its 10% cashback on travel spends and domestic lounge access. It requires disciplined spending to reach the Rs 50,000 annual waiver threshold and justify the higher fees. If you travel often within India and want lounge benefits, this card offers strong value. However, casual spenders or those who do not travel frequently should skip this card due to its higher cost and restrictive fee waiver conditions.
In a decisive call, pick the HDFC Bank UPI Rupay Credit Card ⓘ for everyday cashback and low fees, and the Standard Chartered Easemytrip Credit Card ⓘ if travel rewards and lounges are your priority and you can meet the spend requirements.
What to Check Before You Apply
- Confirm any caps on category cashback to ensure your typical spend is fully rewarded.
- Understand redemption value and ease: cashback is straightforward but verify if any restrictions apply.
- Calculate the monthly spend needed to waive fees on the Standard Chartered Easemytrip card.
- Check forex markup of 3.5% if you plan to use the cards abroad, as this is standard but high.
- Ensure domestic lounge access gates and limits are suitable for your travel frequency, especially the Rs 50,000 quarterly spend requirement on the Easemytrip card.

Comments
No comments yet
Be the first to share your experience with this card.